For investors & partners
Back the full chain of carbon removal
Accredited laboratories, a CRCF-native verification platform and industrial production: one accountable chain, inside one company. Most players own one box. We integrate the column.
Thesis
Three engines, one moat
01 · Measure
The Proof
Accredited specialist laboratories, integrated directly into our digital infrastructure: the measurement layer wired end to end.
02 · Verify
CarbonVision
Built by us, independent by structure: the evidence layer that third-party verifiers judge, governed separately from production. CRCF-native dMRV fed directly by accredited laboratories, and a moat that widens with every developer who builds on it.
03 · Produce
Removal
Industrial biochar production and durable removal credits: the asset that compounds toward 1M.
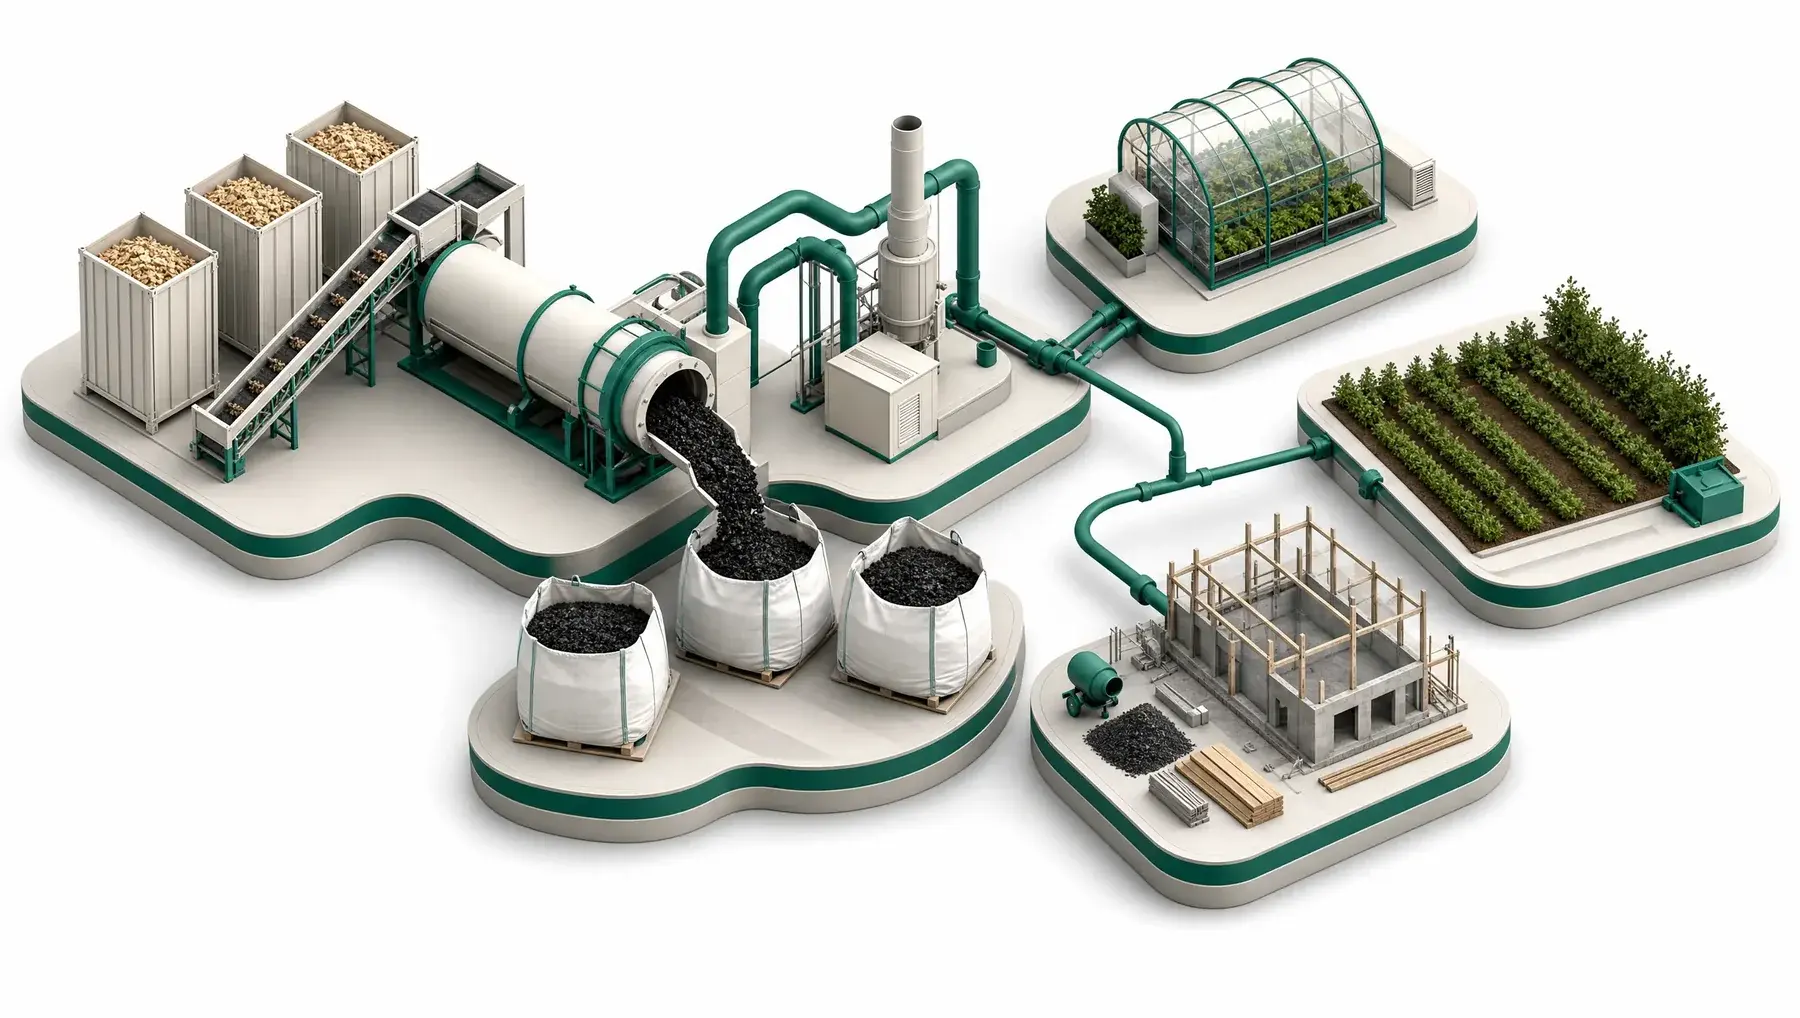
One chain: feedstock, reactor, energy, biochar, offtake
1 MtCO₂e/yr
the ten-year vision
2027
first production target
200+ yrs
durability class · CORC200+
18–26k
tCO₂e/yr · Facility 1 design estimate
Design estimates and targets. Nothing is producing yet.
The moat
Every role, one company
Who holds what, role by role: the capabilities we run today, and the removal methods on our roadmap. Owning the whole chain is what compounds.
| Recarbono | Pure broker | Project dev | Standard | |
|---|---|---|---|---|
| Integrated accredited analysis | ● | ○ | ○ | ○ |
| dMRV platform | ● | ○ | ○ | ● |
| Develops projects | ● | ○ | ● | ○ |
| Generates credits | ● | ● | ● | ○ |
| Pyrolysis-unit engineering | ● | ○ | ○ | ○ |
| Advanced-carbon R&Droadmap | ◇ | ○ | ○ | ○ |
| Enhanced rock weatheringroadmap | ◇ | ○ | ○ | ○ |
| Blue carbonroadmap | ◇ | ○ | ○ | ○ |
● held today · ◇ on our roadmap
Why now
The durable market is biochar, and the EU niche is open
Durable removal is where the money is moving, biochar is where durable removal actually happens, and the mid-size European segment we build for is still under-served. The timing is the thesis.
~90%
of delivered durable CDR to date is biochar
~290
corporate biochar buyers (roughly 5× any other method)
683 kt
biochar removal already delivered
>50%
of EU biochar output still from sub-2,000 t/yr plants
The capital window is open, and the one-big-park model is faltering: a leading EU biochar developer raised €25M and then cancelled its flagship single-park build on financing conditions. Our repeatable, modular SPV model spreads that risk across replicable units instead of concentrating it in one. The same blueprint, financed site by site.
Sector figures: CDR.fyi and European Biochar Industry data, latest full-year set (2025). Not Recarbono projections.
The market
How removal gets financed
Durable carbon removal is built with two different kinds of capital, and it is worth being precise about which does what: they sit on different balance sheets and carry different risk.
Equity
Capital that owns the infrastructure
Equity builds the physical and digital assets: production units, the integration with accredited laboratories, the verification platform. It takes construction and execution risk, and it owns the measurement layer that compounds across every project developed on it.
Forward offtake
Capital that secures the tonnes
A pre-purchase of future certified removals at a price agreed today. It is how buyers lock scarce durable supply before compliance demand tightens, and how capacity gets built in the first place. Different instrument, different risk: the exposure is delivery, not enterprise value.
De-risked by measurement
The risk in any forward removal purchase is that the tonnes cannot be certified on delivery. We own the measurement chain end to end and route every batch through accredited specialist laboratories; the failure mode is engineered out, not insured against.
Transparency from day one
Partners see the evidence trail as it accumulates in CarbonVision (batch records, laboratory results, the audit pack) rather than a certificate at the end.
Priority allocation
Early commitments take priority on first-site volume, with delivery schedules agreed in the contract rather than assigned after the fact.
Built for the EU framework
Methodology and evidence are built to the strictest reading of the EBC and WBC standards, the Puro.earth and Isometric methodologies, and the CRCF, so the tonnes remain defensible as the rules harden.
Local co-benefit, no greenwash
Feedstock is fire-risk residue from the land around each facility. The co-benefits are real and we never count them as extra carbon.
Auditable from day one
The full counting method is published before the first credit exists: every gate, every measurement, every reconciliation rule. You can audit the standard now and watch it hold as the first site comes online.
R&D vision
One carbon platform, later
The honest headline: for a biochar producer today the carbon credit is the product. Downstream materials are how we premiumise and protect it, not how we replace it. One feedstock, one process, several destinations; only some keep the removal intact, and we draw that line where the standards draw it.
Soil amendment & C-sink
Agronomy · carbon credit
The revenue engine, where the removal credit is issued and most of the value sits.
Co-composting & fertiliser
Compost · organic fertiliser
Biochar charged before it reaches the field: worth more than raw char, and the sink survives.
Manure, bedding & husbandry
Livestock operations
Europe's largest biochar market by volume; the material still ends its life in soil, so the removal holds.
Construction: concrete & asphalt
Cement · ready-mix · roads
The only product route the EU CRCF permits. First biochar-asphalt credits were issued under Puro.earth in 2025, reportedly at a premium.
Filtration & activated carbon
Water · air · gas treatment
Attractive as a product business, uncertain as a carbon claim: spent media is typically burned, which voids the removal. We research it as the former and never count it as the latter.
carbon stays stored (the removal holds)
carbon at risk at end of life (a product, not a credit)
Next step
Want the full picture?
This page is the public version of the argument. The investor brief goes further: the facility plan, the measurement architecture, the unit economics and the revenue stack (credits, biochar product, heat and engineering).
Two conversations start here: backing the company (equity in the infrastructure) or securing the tonnes (a forward-offtake portfolio). Tell us which is yours.
Built by petroleum, mechanical and legal-finance operators. Meet the founders →
How we operate
Every number on this site is one we can evidence, and the method behind them is published in full. The whole company is built on a single premise: a claim you cannot prove is worth nothing, and one you can prove is worth a premium.